
Most people treat the S&P 500 like a scoreboard. Green means good. Red means bad. The day’s number is the whole story.
That habit is understandable, and it’s also where a lot of investors go wrong.
The S&P 500 is the central reference index for large-cap U.S. equities. It reflects the strength of American corporations, the direction of capital flows, and the confidence of investors worldwide. Read closely, though, it behaves less like a scoreboard and more like a pressure gauge. Every session, it quietly reflects earnings expectations, liquidity conditions, interest rates, and how heavily the market leans on a few giant companies.
FintechZoom.com SP500 is useful in that context because raw price moves alone tell you very little. The real signal comes from connecting sector shifts, earnings revisions, inflation pressure, interest rate changes, and market flows into one picture.
This matters because knowing that the index moved is easy. Knowing why it moved is what gives the move meaning.
That’s the lens this article uses.
In short: FintechZoom.com SP500 is not just about tracking whether the index closed higher or lower. It focuses on why the S&P 500 moves by looking at market breadth, sector leadership, earnings expectations, Treasury yields, inflation, and liquidity conditions together.
Understanding the Structure of the S&P 500
Before we read the gauge, it helps to know how it’s built.
The S&P 500 is a market-capitalization-weighted index made up of 500 leading publicly traded U.S. companies selected according to index methodology. Because some companies have more than one share class, the number of individual trading lines can exceed 500. Because larger companies carry more weight, the index’s performance can sometimes be driven disproportionately by its biggest constituents.
That’s important when you hear that “the market was up today.” The S&P 500 may be higher even when many individual stocks are flat or falling. For a pension fund manager and for someone checking a retirement account on a phone, the index serves as the same broad reference point, even if their reasons for watching it differ considerably.
The index is commonly referenced under the symbol SPX in market data contexts.
What Is FintechZoom.com SP500?
FintechZoom.com SP500 refers to a market-focused way of analyzing the S&P 500 using price action, sector rotation, earnings trends, interest rates, inflation, and liquidity signals. It brings together market performance data, sector information, macroeconomic context, earnings insights, and liquidity-related signals so readers can look beyond the headline number.
Think of the difference between a weather report and a forecast. One tells you it’s raining. The other helps explain why, what may happen next, and whether you should change your plans.
That distinction matters in financial markets. A 1% move in the S&P 500 can mean very different things depending on what caused it.
What Readers Should Look For
- Up-to-date S&P 500 performance tracking, so you can follow moves as they happen
- Sector rotation monitoring, because leadership often shifts before the headline story catches up
- Corporate earnings trend analysis, to distinguish durable growth from one-off surprises
- Inflation and interest rate analysis, since both can quickly change how equities are valued
- Market flow and liquidity signals, which can help explain price moves that aren’t immediately obvious from company fundamentals
- Volatility context, to put sudden market swings in perspective
Together, these turn passive index watching into a more structured way of reading the market.
The S&P 500 as an Economic Barometer
The index spans technology, healthcare, finance, energy, consumer goods, industrials, and other major parts of corporate America. That breadth is one reason the S&P 500 is watched far beyond trading desks.
It doesn’t measure the entire U.S. economy, but it provides one of the clearest market-based snapshots of large publicly traded American businesses. The index covers approximately 80% of U.S. equity market capitalization.
When the index trends higher for a sustained period, investors are often responding to some combination of stronger earnings expectations, easier financial conditions, improving confidence, or a greater willingness to pay for future profits. When it declines persistently, the pressure usually shows up somewhere specific: weaker margins, tighter financial conditions, falling earnings expectations, or a shift in investor risk appetite.
For investors, the practical takeaway is this: the duration and breadth of a trend often tell you more than any single day’s move.
Market Capitalization Weighting and Concentration Risk
Here’s where the headline number can mislead you.
Because the index is market-cap weighted, larger companies move it more than smaller ones. In periods when a handful of mega-cap stocks dominate returns, the index can look strong while a much larger portion of the market is barely moving.
At face value, the index looks healthy. Underneath, the picture may be much narrower.
That’s why it’s worth checking market breadth and sector concentration alongside the headline level. A rally supported by broad participation tells a different story from one carried primarily by a few very large companies. The distinction isn’t automatically bullish or bearish. It simply tells you how much of the market is actually participating.
Earnings Yield Versus Treasury Yield
This section gets a little technical, but the idea behind it is intuitive.
Large asset managers often compare the earnings yield implied by equity valuations with the yield available from long-term Treasury securities. In simple terms, they’re asking whether stocks offer enough potential return to justify taking more risk than a relatively safer bond.
When bond yields rise sharply, equities generally face a tougher valuation environment because investors can demand a higher return. When yields fall, equities can become relatively more attractive, particularly when earnings expectations remain healthy.
This relationship is one reason the bond market matters so much to the S&P 500. If you’re wondering whether an equity rally has room to continue, looking at Treasury yields alongside earnings expectations can provide a more useful answer than the index chart alone.
Long-Term Performance and Historical Benchmarks
Over long periods, the S&P 500 has produced substantial returns, particularly when dividends are reinvested. The commonly cited figure of roughly 8–10% annually is a useful long-run historical reference when dividends are reinvested, but it is not a guaranteed annual return.
An average is a comfort, not a guarantee. Strong years and painful drawdowns both fit inside that long-run figure. Investors only experience the average by living through the extremes.
Valuations follow a similar pattern. Historical price-to-earnings levels provide useful context, but they shouldn’t be treated as a fixed ceiling or floor. Interest rates, earnings growth, inflation, and investor expectations all influence what the market is willing to pay for a dollar of earnings, and those conditions change.
Dividend yields and market capitalization figures are equally context-dependent. In recent years, a relatively small group of mega-cap companies has accounted for a significant share of total index weight, which is one reason market breadth deserves as much attention as the headline level.
The broader principle is more useful than any single historical number: context matters more than averages.
S&P 500 Compared to Other Major U.S. Indexes
The S&P 500 is the most widely followed benchmark, but it isn’t the only one. The differences matter more than they first appear.
The Nasdaq 100 includes 100 large non-financial companies and leans heavily toward technology and growth. That focus can bring higher volatility and greater sensitivity to interest-rate expectations.
The Dow Jones Industrial Average tracks 30 large companies and uses price weighting instead of market-cap weighting. That means a company’s share price, rather than its overall market value, determines how much influence it has on the index, which can distort how well it represents the broader economy.
The S&P 500 uses market capitalization and includes companies from a wider range of industries, making it a particularly useful benchmark for large-cap U.S. equities. That said, it should not be mistaken for a complete representation of every part of the American economy.
Valuation Framework: Understanding Multiple Expansion and Compression
Price-to-earnings multiples sit at the center of most S&P 500 valuation debates. But a multiple is never just a number. It’s a reflection of what investors expect from future cash flows, economic stability, interest rates, and risk.
When growth expectations are strong and inflation stays contained, investors may be willing to pay more for each dollar of projected earnings. That’s multiple expansion. When uncertainty rises or interest rates climb, investors may demand a greater return for taking equity risk, and multiples can contract. That’s valuation compression.
Liquidity is another important part of the equation. During periods of easier financial conditions, abundant capital can support risk assets and keep valuations elevated. When conditions tighten, multiples can contract even if corporate earnings have not yet deteriorated.
That’s the distinction worth remembering. A rising index can be powered by growing earnings, higher valuations, or both. The healthiest rallies tend to have fundamental support behind them. When prices rise mainly because investors are willing to pay increasingly higher multiples, without comparable improvement in earnings expectations, the market can become more vulnerable to disappointment.
How to Read an S&P 500 Move in Five Minutes
This is perhaps the most useful habit to develop when following the index.
When the S&P 500 moves sharply, don’t stop at the percentage change. Run through five questions.
1. How large is the move?
Start with the obvious. Is the index moving 0.3%, 1%, or several percent? A small daily fluctuation deserves a different interpretation from a sudden major repricing.
2. How broad is the move?
Check how many stocks are participating. If the index is rising while relatively few companies are responsible for most of the gains, the headline number may look stronger than the underlying market actually is.
3. Which sectors are leading?
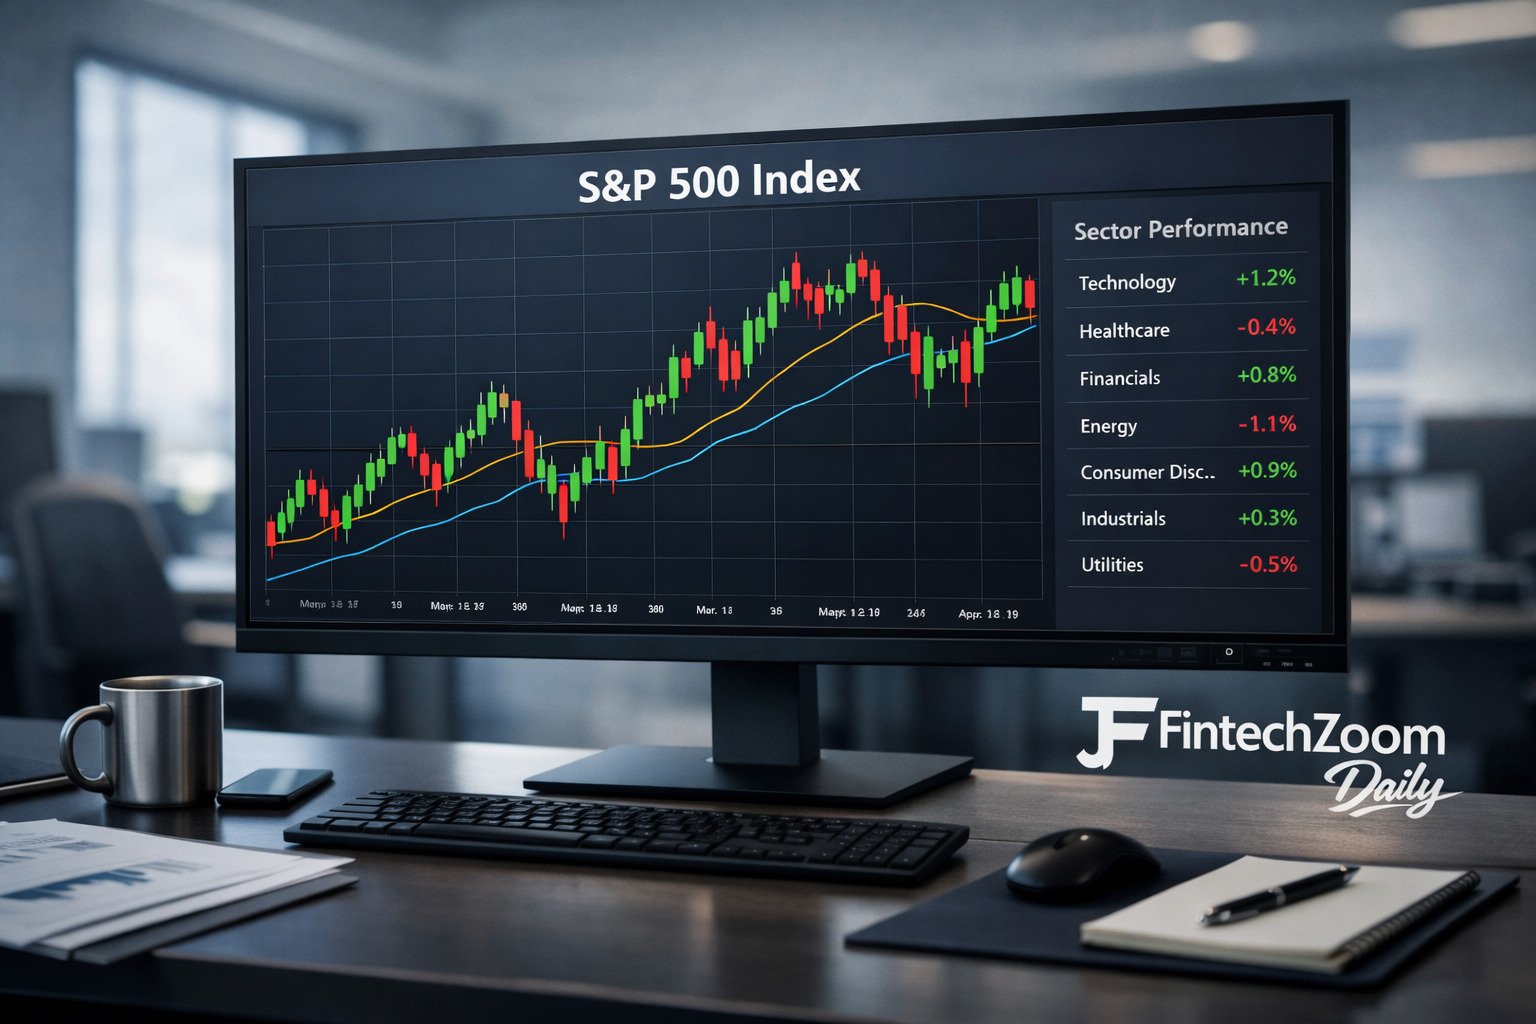
Technology, financials, energy, healthcare, and consumer sectors respond differently to changes in economic expectations. Knowing which groups are leading can tell you more about the market’s current narrative.
4. What are Treasury yields doing?
A sharp move in Treasury yields can change the valuation equation for equities, particularly for companies whose expected cash flows lie further in the future.
5. What are earnings expectations doing?
Finally, ask whether analysts and companies are becoming more or less optimistic about future profits.
If price, breadth, sector leadership, yields, and earnings expectations all point in the same direction, the move deserves closer attention. If they disagree, the headline index number may be telling only half the story.
Reading the S&P 500 With More Context
Bringing the Picture Together
Markets move fast, and fragmented information makes volatile days harder to read. The value of following FintechZoom.com SP500 is that it places price performance alongside sector information and broader market indicators, making it easier to ask the right follow-up question: what actually changed underneath the headline?
Sector Rotation Monitoring
Money doesn’t sit still. It rotates between sectors as economic and market conditions change. During some inflationary periods, energy and financials may benefit. During slower-growth environments, defensive areas such as healthcare and consumer staples may attract relatively more attention.
Watching these shifts can help investors understand whether market leadership is changing, rather than simply assuming yesterday’s leaders will remain tomorrow’s leaders.
Earnings Revision Interpretation
Markets often care more about where earnings are heading than where they’ve been. Forward guidance can move prices more than reported results, because investors are constantly trying to estimate future profitability.
Upward revisions can support valuations. Downward revisions can pressure them, sometimes even when the current quarter looks fine on the surface. Tracking the direction of expectations gives investors a more forward-looking view instead of relying only on historical results.
Volatility in Context
Not every volatility spike is a warning sign. Some sharp moves reflect scheduled economic announcements, changes in interest-rate expectations, portfolio rebalancing, or temporary liquidity conditions. Others signal a deeper change in market expectations.
Context is what helps separate genuine stress from passing turbulence, and what keeps a difficult afternoon from becoming a poor long-term decision.
Macro Forces Driving S&P 500 Performance
Earnings tell you what companies are doing. Macro forces tell you what the environment is doing to them.
Federal Reserve Policy Transmission
Interest rates reach equity valuations through discount-rate mechanics. Higher rates can increase the cost of capital and put pressure on valuation multiples. Lower rates can support valuations, particularly for growth-oriented companies.
Markets also react to the Federal Reserve’s tone, not just its actions. A change in language about inflation, employment, or future policy can move markets before an actual rate change takes place.
Inflation Regimes and Margin Sensitivity
Not all inflation is equal. Demand-driven inflation can coincide with strong consumer spending and rising revenues. Supply-driven inflation can squeeze margins when input costs rise faster than companies can raise prices.
Knowing the source of inflation matters because different industries experience the pressure differently.
Bond Market Correlation
When Treasury yields rise, the relative appeal of fixed-income assets can shift. Growth stocks can be particularly sensitive because a larger portion of their expected value may come from profits further in the future.
That doesn’t mean rising yields automatically cause stocks to fall. It means the relationship between yields, earnings growth, and valuation deserves attention.
Currency Strength and Multinational Earnings
A stronger dollar can reduce the reported value of overseas revenue when it’s converted back into U.S. currency. For multinational companies within the S&P 500, currency movements can therefore affect reported earnings even when the underlying business hasn’t materially changed.
Liquidity Cycles and Capital Flow Dynamics
If earnings are the engine, liquidity is one of the forces that determines how easily it runs.
Central bank policy, credit conditions, institutional positioning, and investor risk appetite can all influence how much capital flows into equities. When financial conditions ease, risk appetite can strengthen. When they tighten, investors may become more selective and shift toward defensive assets.
There’s also a mechanical layer that rarely makes headlines. Pension funds, asset managers, and other large investors periodically rebalance portfolios. Those adjustments can create buying or selling pressure that has little to do with the economic news of that day.
So when price action seems disconnected from the headlines, liquidity and positioning are often worth examining.
Historical Case Studies in Index Behavior
Theory is useful. History shows how these forces interact in practice.
2008: The financial crisis combined severe credit stress, falling earnings expectations, and a sharp deterioration in liquidity. The S&P 500 reflected more than weak corporate profits. It reflected a financial system under extraordinary pressure.
2020: The pandemic produced a rapid market selloff followed by aggressive monetary and fiscal support. The speed of the subsequent recovery demonstrated how quickly financial conditions and investor expectations can shift.
2022: Rapid interest-rate increases aimed at combating inflation created significant pressure on equity valuations, particularly among growth companies whose valuations depended heavily on future earnings and lower discount rates.
The important lesson across all three periods is that policy, liquidity, earnings, and expectations rarely operate independently. The index responds to how those forces interact.
Market Cycles and Sector Rotation Dynamics
Economic cycles often hand leadership from one group of sectors to another. Recognizing where conditions stand can help investors think ahead of shifts rather than simply reacting to them.
- Early cycle: Financials, industrials, and consumer discretionary stocks can benefit as economic growth and credit conditions improve.
- Mid cycle: Technology and other growth-oriented sectors may gain ground as corporate investment and earnings momentum strengthen.
- Late cycle: Defensive areas can become more attractive as growth slows and investors grow more cautious.
- Recession phase: Utilities, healthcare, and consumer staples can demonstrate relative resilience because demand for many of their products and services is less economically sensitive.
These patterns aren’t a clock you can set. They’re better viewed as a framework for understanding changing conditions rather than a guarantee about which sector will outperform next.
Passive ETFs and Structural Market Mechanics
The growth of passive investing has changed how capital moves through equity markets.
Large ETF flows can affect demand across index constituents, while scheduled rebalancing can create mechanical buying or selling that isn’t necessarily based on a new view of a company’s fundamentals.
That distinction matters. Not every sharp market move represents a fundamental judgment about corporate profitability. Sometimes market structure and positioning are part of the explanation.
For investors, understanding that difference can help separate temporary liquidity pressure from a genuine change in the underlying outlook.
Dividend Yield Versus Growth Exposure
Dividend-paying stocks can provide income and may offer relative stability in some uncertain environments. Growth stocks can deliver stronger capital appreciation during favorable expansion phases, but they often experience larger swings when interest-rate expectations shift.
You don’t necessarily have to choose one side. The more useful question is how income, growth, valuation, and risk fit together within a portfolio, and within the investor’s time horizon.
How Investors Gain Exposure to the S&P 500
Most investors gain S&P 500 exposure through ETFs, index funds, or similar products designed to track the index. Widely followed ETFs such as SPY, VOO, and IVV provide diversified exposure to the index without requiring investors to select individual companies.
It’s worth distinguishing the index itself from these investment products. The S&P 500 is the index. ETFs such as SPY, VOO, and IVV are investment vehicles designed to track its performance.
Index methodology also evolves over time. Constituent changes and periodic reviews help keep the index aligned with its eligibility rules and market representation goals.
Strategic Portfolio Construction Using S&P 500 Signals
The same market information can serve different investment objectives.
Long-Term Investors
Focus on sustainable earnings growth, diversification, and valuation relative to the broader interest-rate environment. Avoid allowing a single market theme to dominate the portfolio simply because it has performed well recently.
Swing Traders
May pay closer attention to sector momentum, volatility, earnings revisions, and changes in market breadth. The objective is less about understanding the entire economy and more about identifying shifts in short- to medium-term market behavior.
Risk-Averse Allocators
May place greater emphasis on broad diversification, income stability, and defensive exposure when economic uncertainty increases. Protecting what you have often comes before chasing more.
Growth-Oriented Investors
Often pay particular attention to innovation-driven sectors when interest-rate conditions become more supportive and earnings expectations remain strong.
These are frameworks, not formulas. Market conditions can change faster than any predefined allocation strategy.
Core Drivers Influencing S&P 500 Performance
| Market Driver | Economic Mechanism | Potential Market Effect | What to Watch |
|---|---|---|---|
| Federal Reserve rates | Changes discount rates and financial conditions | Can expand or compress valuations | Policy direction and language |
| Inflation | Affects margins, demand, and interest rates | Changes earnings and valuation expectations | Trend and underlying source |
| Treasury yields | Changes relative appeal of bonds and equities | Particularly affects rate-sensitive valuations | Direction and speed of yield moves |
| Market flows | Changes buying and selling pressure | Can amplify short-term momentum | Fund flows and positioning |
| Earnings guidance | Changes expectations for future profits | Can trigger valuation repricing | Upward or downward revisions |
| Market breadth | Shows how widely gains or losses are distributed | Helps assess underlying participation | Advancing vs. declining stocks |
Keep this framework close. It gives daily index swings a structure, so you can see the forces behind the number rather than just the number itself.
Risk Considerations and Structural Limitations
Diversification is one of the S&P 500’s biggest strengths, but it has limits.
The index remains exposed to concentration risk when a small group of mega-cap companies accounts for a large share of its movement. Monetary policy also works with a lag, while geopolitical shocks, credit stress, and liquidity changes can distort short-term price action.
No index removes systemic risk. Owning hundreds of companies spreads company-specific risk, but it doesn’t protect an investor from a broad market decline. The S&P 500 can reduce the risk of concentrating everything in one company without eliminating the risk of being invested in equities.
Frequently Asked Questions
Is the S&P 500 overvalued?
Not automatically. There is no single valuation level that automatically makes the index overvalued or undervalued. The more useful comparison is between current valuations, expected earnings growth, interest rates, and the risks investors are pricing into the market.
Why can the S&P 500 rise when many stocks are falling?
A small group of very large companies can outweigh declines across many smaller ones. Because the index is market-cap weighted, its largest companies have a much greater influence on its performance. A relatively small number of very large companies can therefore lift the index even when many other constituents are declining.
How do rate cuts affect the S&P 500?
Rate cuts usually support stocks, but the reason behind the cuts matters. Lower rates can lift equity valuations by reducing discount rates and easing financial conditions. If rates are falling because the economy is weakening sharply, declining earnings can offset some of that benefit.
Can the S&P 500 predict a recession?
No, not reliably on its own. However, sustained market weakness combined with deteriorating earnings expectations, tighter financial conditions, and weakening economic indicators can provide clues about rising recession risk.
How do ETF flows influence the S&P 500?
ETF flows can move many index stocks at once, but they don’t always reflect a change in fundamentals. Large flows into or out of index-tracking funds can affect demand across many constituents at the same time. However, ETF flows are only one part of market activity and should not automatically be interpreted as proof that fundamentals have changed.
Which sectors tend to perform well during inflation?
Energy and materials have often held up better during inflationary periods, though results depend on what’s driving inflation. Energy and materials can benefit from stronger commodity prices in some inflationary environments, while companies with limited pricing power may face margin pressure. The effect depends on the source and persistence of inflation.
What is the long-term average return of the S&P 500?
Roughly 8–10% per year over long periods, with dividends reinvested. The index has generated substantial long-term returns when dividends are included. Annual results vary widely, however, and historical averages should be treated as long-term context rather than a promised yearly return.
Is the S&P 500 safer than individual stocks?
Yes, for company-specific risk, but not for broad market risk. It reduces company-specific risk by spreading exposure across hundreds of large companies and multiple industries. It remains exposed to broad market risk, so diversification does not eliminate losses during major market declines.
How often is the S&P 500 rebalanced?
Quarterly, with additional changes made when needed. The S&P 500 is reviewed and rebalanced on a quarterly schedule, typically after the close on the third Friday of March, June, September, and December. However, constituent changes can also occur outside the regular schedule when corporate actions, eligibility changes, or methodology requirements make them necessary.
Does the S&P 500 include dividends?
No, the standard price index does not include dividends. The standard S&P 500 price index reflects changes in constituent prices and does not include dividend income. Total-return versions of the index account for dividends and their reinvestment.
Structural Concentration and Market Breadth
The headline number can hide what’s happening underneath.
When a narrow group of mega-cap names drives performance, weakness elsewhere in the market can remain invisible for a surprisingly long time. The index can continue climbing even as participation becomes increasingly concentrated.
That’s why breadth deserves attention alongside concentration. A market where gains are spreading across many companies tells a different story from one where the index depends heavily on a small cluster of leaders. Neither situation automatically predicts what happens next, but the difference tells you how the market’s strength is being built.
Forward Outlook: What Investors Should Monitor
The next phase of S&P 500 performance will depend heavily on the durability of earnings, the path of inflation, interest-rate expectations, and broader financial conditions.
Sector dispersion may remain important as different industries respond differently to growth, rates, and technological investment. Liquidity conditions, corporate guidance, Treasury yields, and market breadth are therefore worth watching alongside the daily index close.
The useful question isn’t simply, “Is the S&P 500 going up?” It’s “What is supporting the move?”
Structural Themes Shaping the Next Phase of the S&P 500
A few longer-term forces are already influencing the index.
Artificial intelligence investment is accelerating capital spending across parts of the technology sector. If companies turn that spending into durable revenue and productivity gains, it could support earnings growth. If monetization falls short, however, heavy investment could put pressure on margins.
Demographics and labor-market conditions will shape wage growth, consumer spending, and corporate costs, all of which eventually feed into revenue and profitability.
Fiscal policy, including infrastructure spending and industrial incentives, can support particular industries even when broader growth slows.
On the other side of the ledger, high debt levels and elevated long-term interest rates can place pressure on valuations and limit how far multiples can expand.
For investors, the practical takeaway is to watch capital expenditure, productivity, earnings revisions, and margin stability alongside the usual inflation and employment data. The next major move in the S&P 500 is unlikely to be explained by a single headline. It will more likely come from the interaction between earnings, liquidity, interest rates, and investor expectations.
Quick Take: The S&P 500 becomes more useful when you read it as a market signal rather than a daily score. Market breadth, sector rotation, earnings revisions, Treasury yields, inflation, and liquidity explain what the index is really pricing in. A headline move matters most when these signals point in the same direction.
Conclusion
The S&P 500 is the structural benchmark of American large-cap equities and one of the most closely watched measures of market sentiment. But its real value only shows up when you stop treating it like a scoreboard.
FintechZoom.com SP500 fits into that broader way of reading the market by placing price action, sector movements, earnings information, and macroeconomic context into the same conversation.
In markets this layered, discipline is a genuine advantage. Investors who understand the structural drivers, valuation mechanics, and capital flows behind the index don’t just react better. They tend to see risk earlier and recognize opportunity sooner.
The next time the index moves sharply, try a different first question. Instead of asking whether it went up or down, ask what the move is telling you about earnings, breadth, interest rates, and liquidity.
That small change in perspective can make the S&P 500 much more useful. It stops being just a daily verdict and becomes a way to understand what the market is actually pricing in.
David Harvey is a Financial Markets Analyst specializing in global markets, investing trends, fintech innovation, cryptocurrency and economic developments. He focuses on delivering data-driven financial analysis and simplified market insights for modern readers and investors.